

Price action seems to be confirming my thesis shared ~two weeks ago now.
The market doesn’t care about fundamentals nor guidance, it cares about how to fund the next leg of acceleration. And as no one wants to answer this question - maybe for a reason, it sells and rotates.
Meta Earnings
Another banger quarter, another double beat - excluding the one time legal charge. Fundamentals are extremely strong and coupled with concrete AI ROI in the form of ads targeting and pricing.
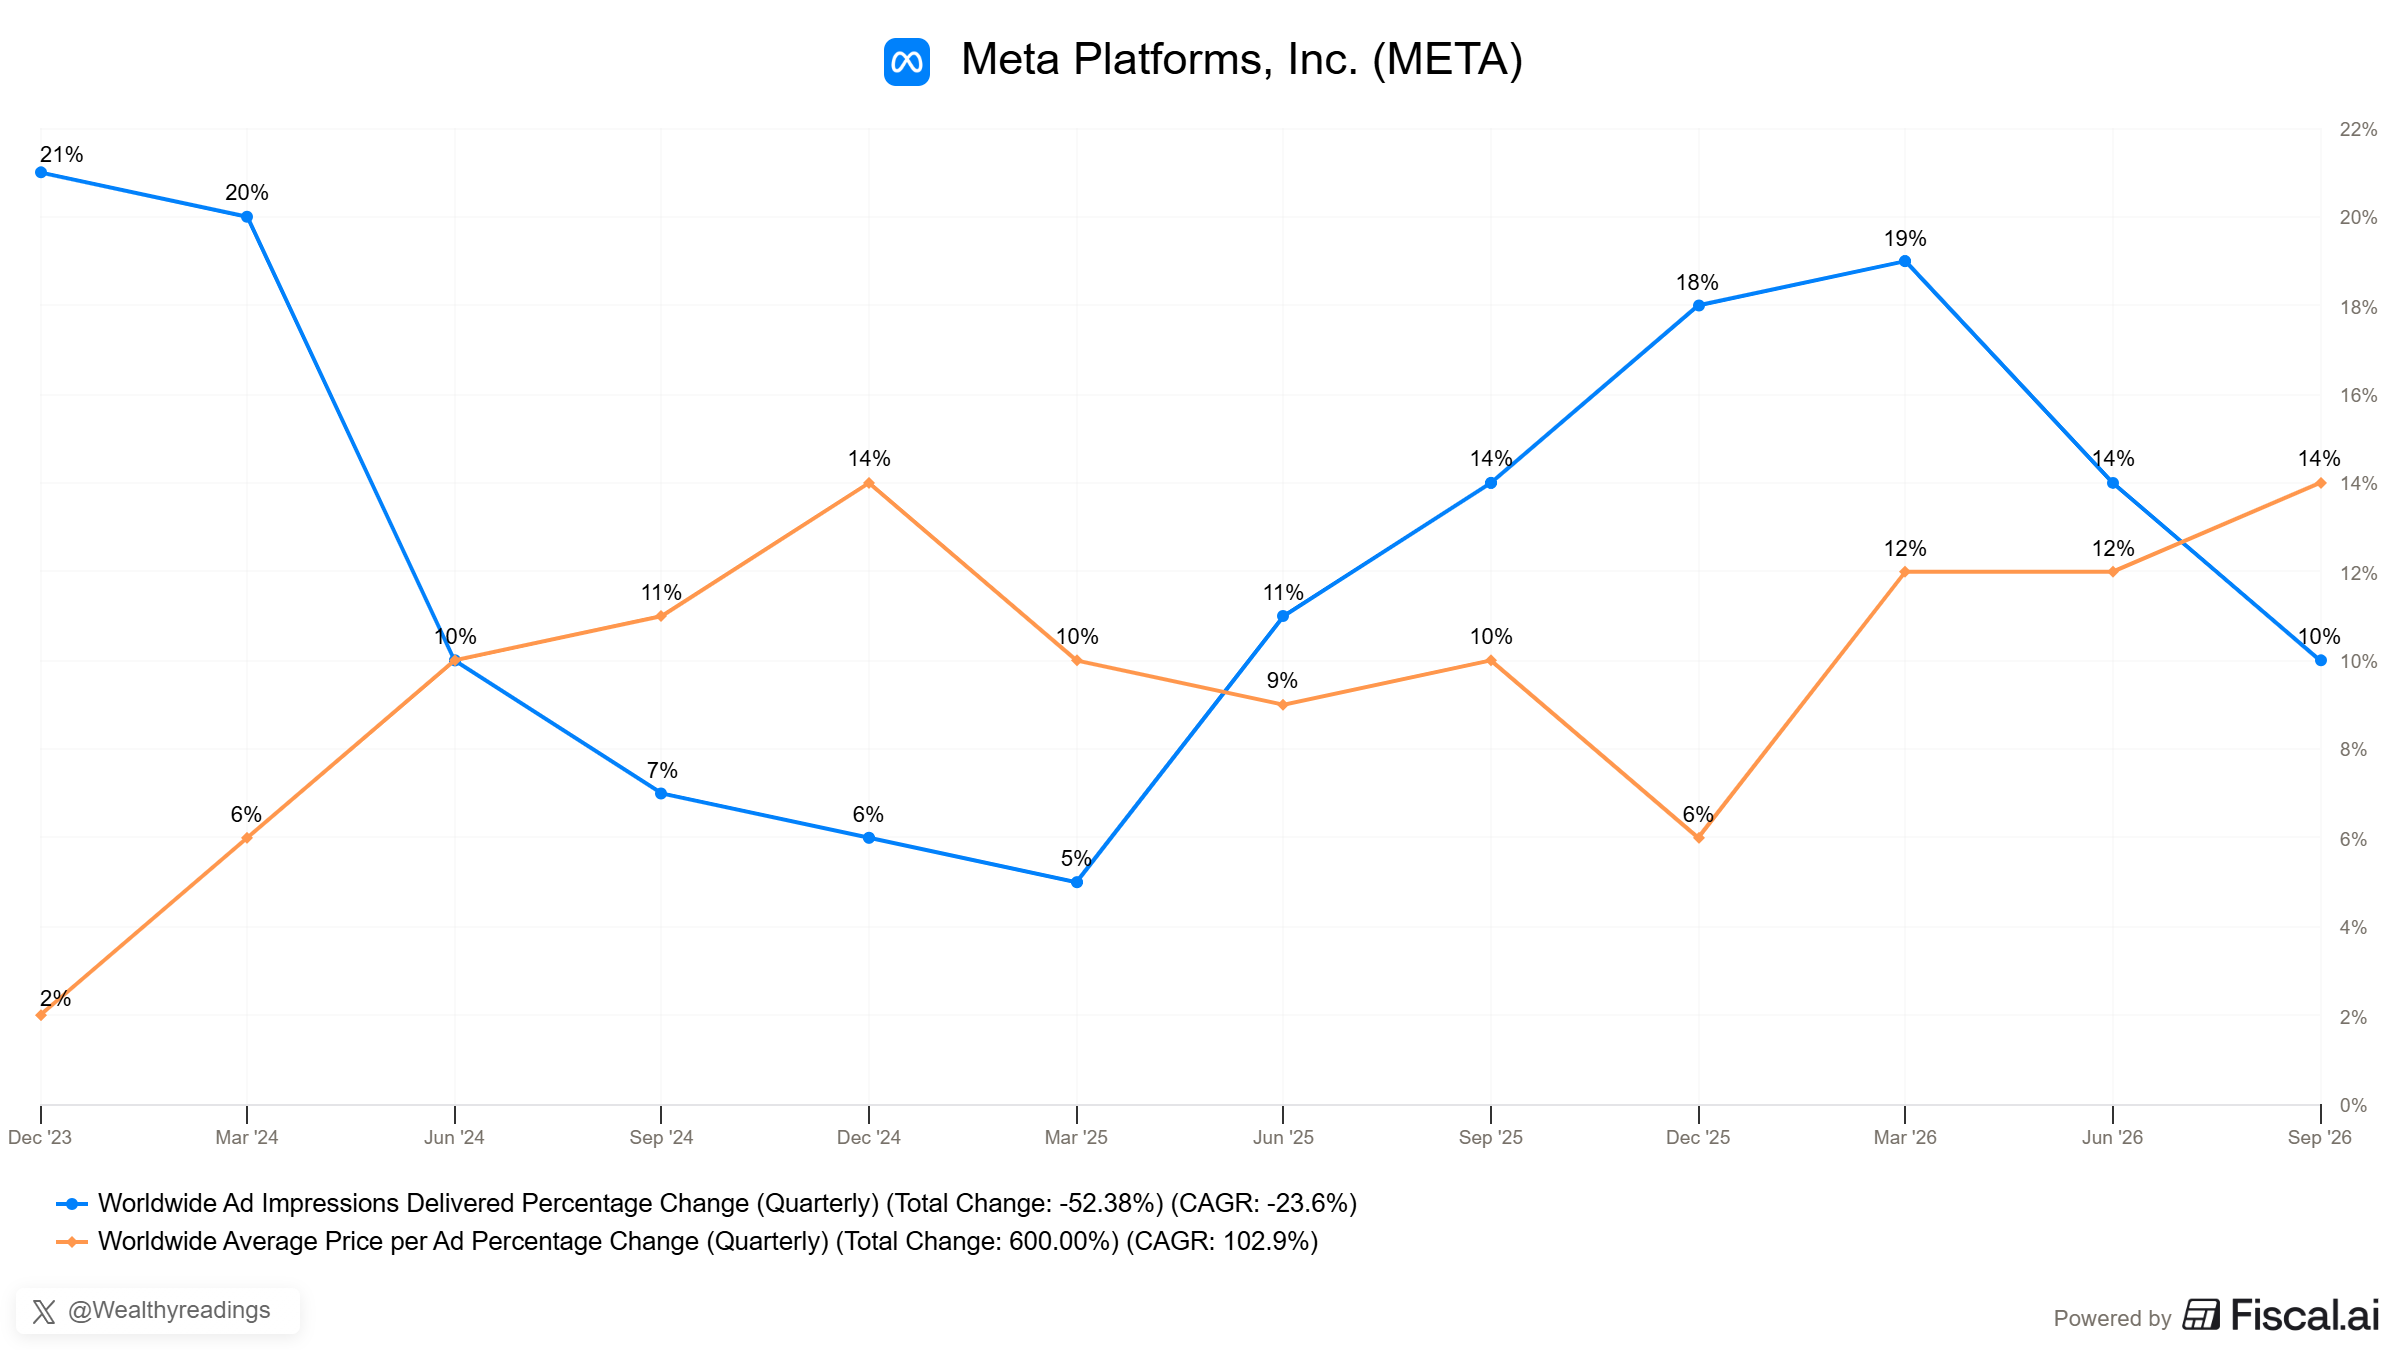
Nothing new, nothing unexpected, just another quarter for Meta.
The call was also as usual, with comments on compute constraints especially after Muse release - which we know requires a lot (really a lot) of compute, and CapEx. The roadmap is unchanged, the reasons are too.
We are still developing our budget and capacity plans for next year, but we expect to continue investing aggressively to support both our core business and emerging AI initiatives.
We want to make sure that we’ve built enough compute to be able to serve what we think is going to be a billion plus people if we can achieve certain compute efficiency targets… that’ll be one of the limiting factors over the next year.
We are, I would say, at the point where we are both evaluating a lot of investment proposals that have attractive return profiles over different time horizons. We want to figure out how we can fund as many of those as possible within the construct of our overall budget and financial goals. But it’s very dynamic.
But the second quote says it all… “We want to figure out how we can fund it”.
Those words confirm my take a few days ago. Not enough compute - we knew that, supply chain constraints - that used to be bullish, yielding delays in buildouts - slowing down ROI, and now harder access to funding - slowing even further.
I shared some days ago I believe the AI bull run would show its limit when megacaps start to fund themselves through dilution, meaning they are starting to struggle finding funds elsewhere. Here an important comment from Susan.
We created this new class of shares with the purpose of creating a publicly traded non-voting stock usable for capital raising, employee compensation, acquisitions, other general corporate purposes… It will expand our funding tools and give us flexibility to invest behind the unprecedented momentum we are seeing… We do not have any specific financing plans to announce at this time, but we thought it was prudent to establish the appropriate capital structure framework to ensure that we have access to a diverse pool of funding sources.
I’m not saying the bull run is over. I am saying this is a sign. Not to ignore.
I have no doubt Muse will be one of Meta’s cash cows in the next years, but the road to get there is complicated and won’t happen with an up-only stock.
No one can argue with Meta is one of the largest and healthiest cash machines on the market. Track record has been amazing and current FCF situation is only due to compute CapEx.
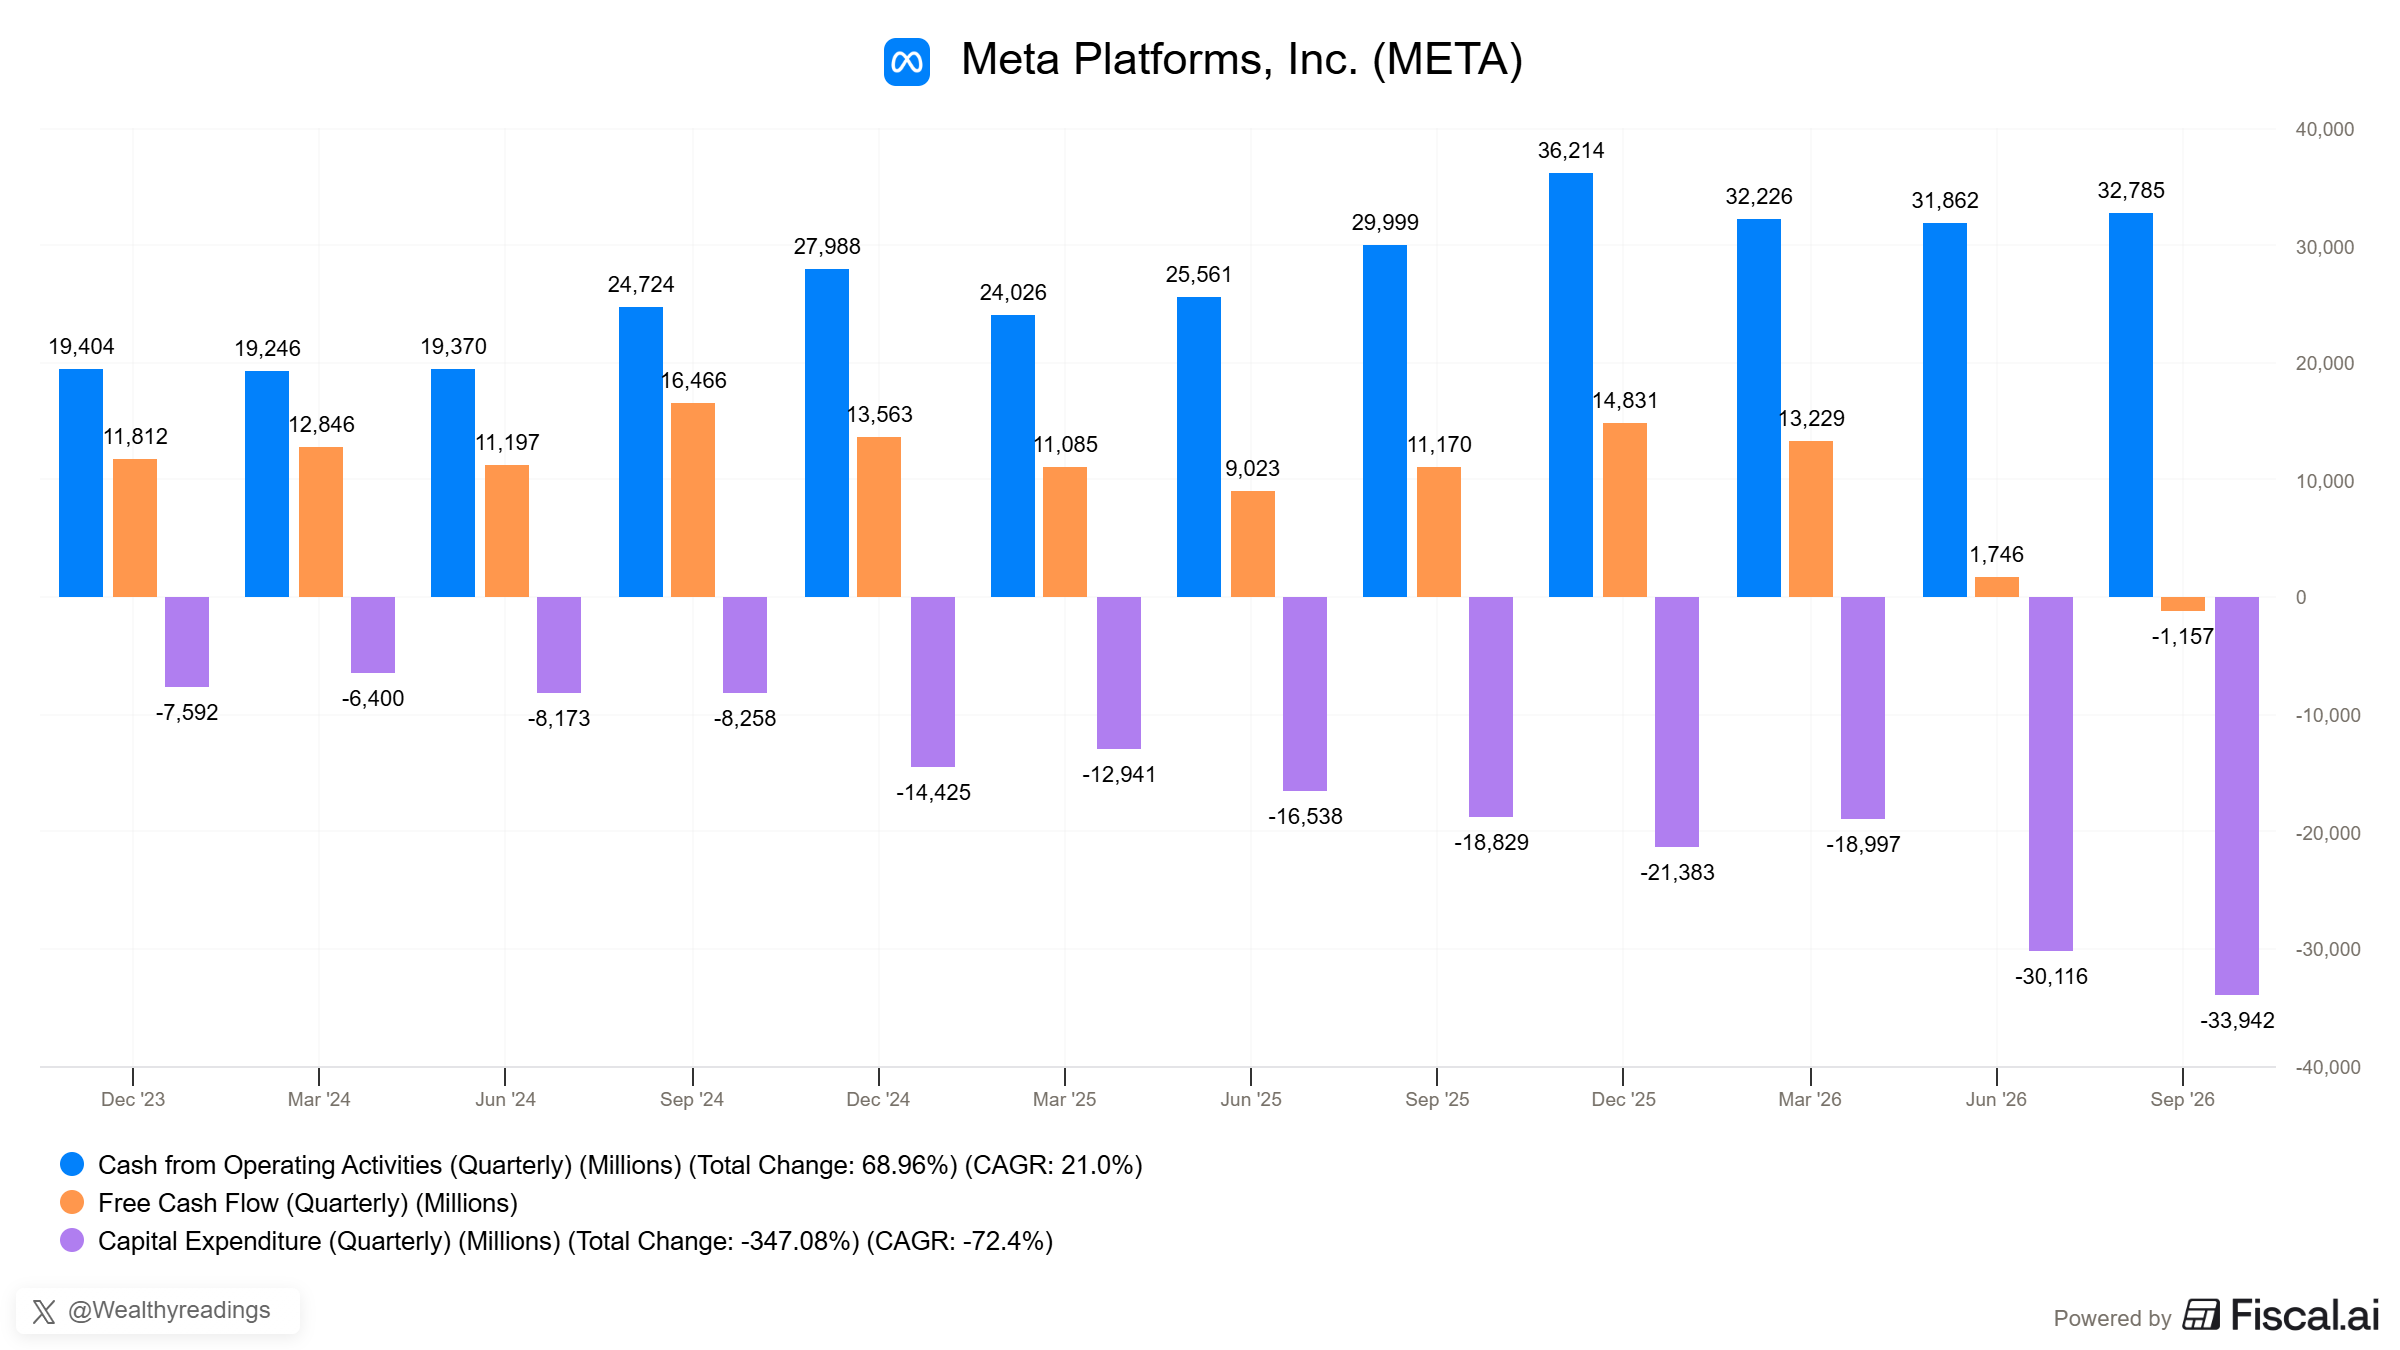
Crystal clear, right?
Meanwhile, the market is repricing its risk as its credit default swap jumped to a new ATH after they released this quarter - which as a reminder was a double beat with very healthy cash generation.
No one is immune.
Once again - I feel this needs to be repeated, I’m not bearish AI, nor buildouts. I am extremely bullish. But I am also bullish airplanes and baggy pants, which doesn’t mean I am buying those stocks. Bullishness and investing are two different things.
Our focus is to make money. Not just buy what we like. That’s consuming. I do not believe AI hardware is the best source of safe returns anymore today, not while other sectors are waking up, breaking out, and receiving tons of liquidity.
Let’s not make this harder than it is…
