

My one short-term bull case for AI hardware always was a Trump taco. A deal or the promise of one that forces the market to reprice funding conditions. I do not see anything else getting these names off their knees fast.
I do not expect a V shape recovery nor a rapid recovery, except if Trump was to stop the war, complete taco. This is the only situation in which I see AI hardware bounce hard and long.
Something just moved. Not a fact yet. But enough to talk about it.
The Iran Rumors
Rumors of U.S. Iran talks started yesterday. I flagged them in the chat and did nothing, we’ve seen this playbook many times. But they continued today and came from a second, separate source, pointing the same way: talks are happening, and moving.
Personally? I struggle to believe it. Iran has no reason to ease pressure before the mid-terms and every reason to let Trump lose them. The only path to a deal is Trump taco so hard he hands them what they want and dresses it up as a win. Which, going into mid-terms, isn’t the least likely outcome. Optics are everything right now.
I have no idea which way it breaks. What I know is, when these rumors start showing like this, the time between smoke and an actual something is usually days. Where there’s smoke, there’s fire.
The thing is I don’t need to believe it. I need the market to.
My motto these last days was capital preservation until I could have a setup to swing. I believe this is what we have today. Some strong names still sitting on their W50 and giving a great risk/reward while rumors continue to make noise. If it dies, I lose a little. If it lands, these move hard and long.
Small, defined downside, asymmetric upside, with a catalyst in progress. That’s not a prediction-market gamble anymore but the exact setup I kept cash aside for.
Capital preservation is still rule #1. But rule #1 comes with conditions, like every position. Mine was a path to peace with Iran. The rumors aren’t a deal but they’re enough to swing it.
SpaceX Earnings - No Surprises
Numbers were excellent, we knew they’d be. We knew fundamentals weren’t the core of the issue: funding is.
Demand and fundamentals aren’t the problem. They’re as strong as they’ve ever been. The market is pricing one thing only: financing risk.
One quote and one image to make the bull case.
We ended the quarter with substantial backlog totaling $63B as of September 30, of which $17.5B was recognized as deferred revenue. Approximately $42B of this backlog is expected to be recognized within the next year. Looking ahead, demand remains robust across all three segments, particularly in our cloud services business. We remain on track to deliver our previously stated goal of $100B in ARR by the end of this year, defined as annualized revenue based on the month of December.
What we are seeing in the market is extraordinary. At current pricing, new compute deployments are generating a payback of less than a year.
Massive revenue growth, EBITD/EBITDA positive; not only are demand and visibility here, but compute generates cash flow.
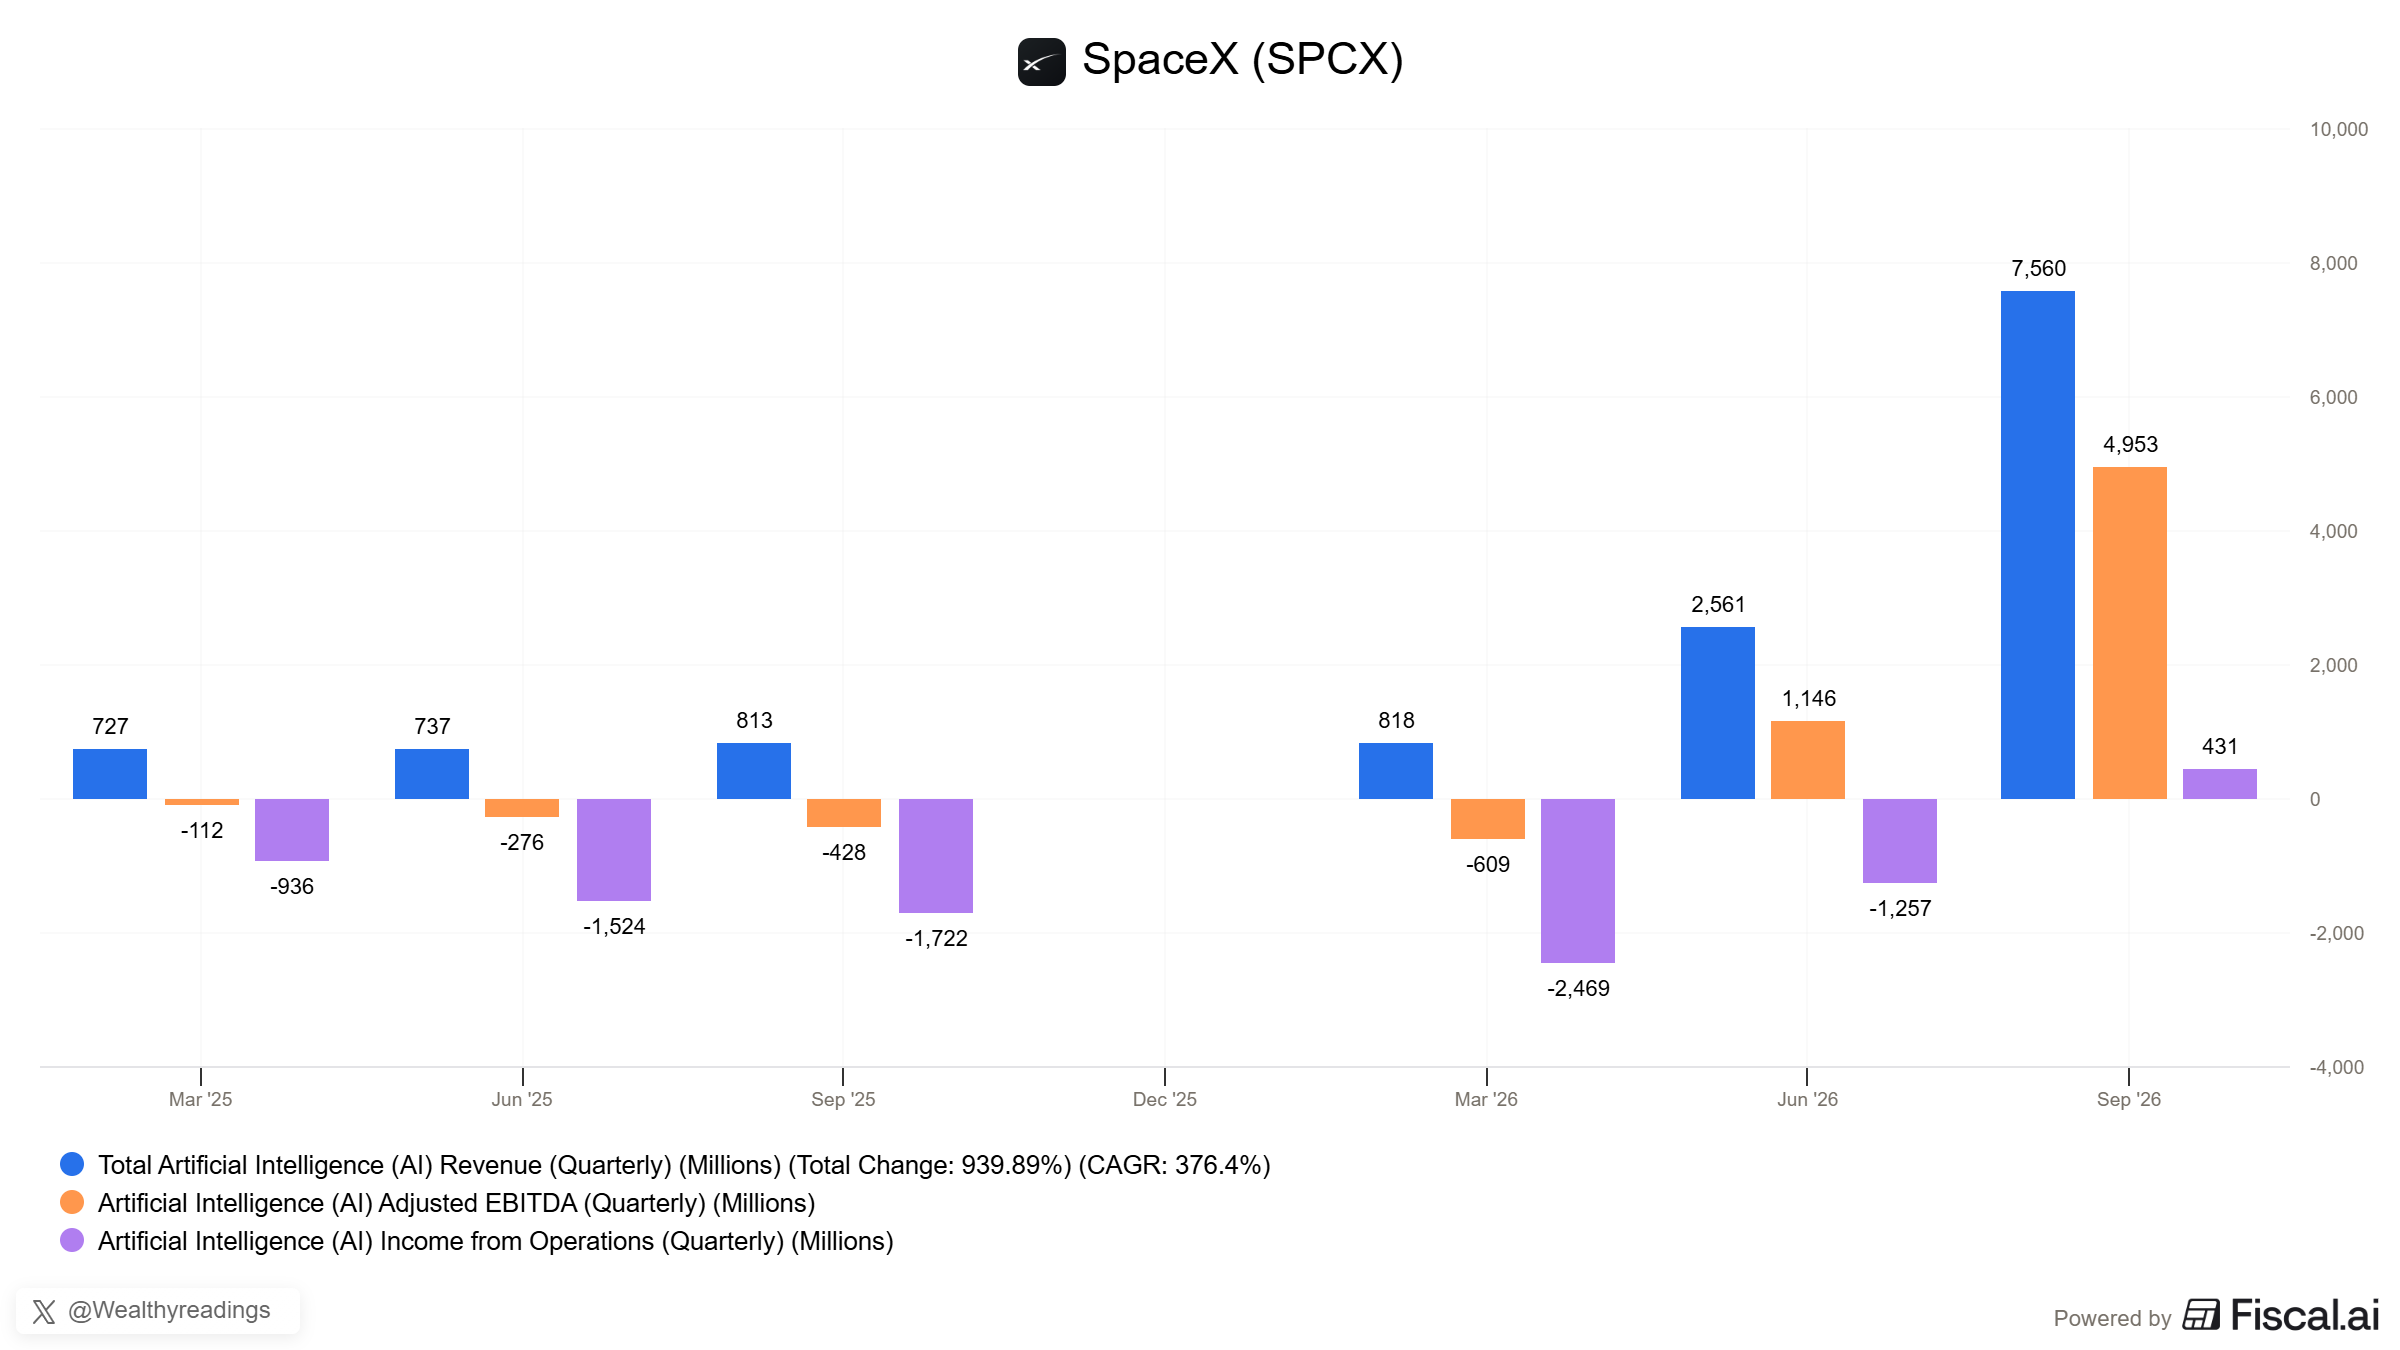
But through the whole call, funding isn’t really mentioned.
Elon talks a lot about what will be built, 220,000 GB300s plugged online per month, 10 gigawatts of compute in 2027 with a path to 20 if everything goes well, and of course constant increase and acceleration of CapEx.
But nothing about funding, except this line.
We are investment grade, have a very strong balance sheet, and there are a number of available pools of debt capital we’re talking to… and the payback period is very short, so this starts to fund itself in a pretty near-term situation.
So, “we can borrow”.
Never doubted that, what I doubted - and continue to, it’s at what rate? And at what volume? One bank accepting to take risks won’t be enough.
For context, 10GW are estimated to cost ~$350B. And that would be Elon’s base case for 2027. For more context, Google spent ~$132B over the last twelve months in CapEx, guided to ~$175-185B FY26, and funded it through both cash flow and debt.
Better ROI helps. it shows a viability that didn’t exist two quarters ago and could help negotiate lower yields. But the core is unchanged: financing the buildout at a cost that works, and today’s cost is very high and risky for lenders.
I love Elon. The guy made a car fly for no reason, stuff I’m here for. But he’s a dreamer and a world-class talker, and I don’t take his targets as facts. Meanwhile, people who called him a fraud for years due to Tesla are suddenly quoting him as proof funding and energy are solved because they are bullish on neoclouds...
So what actually changed?
Not the facts. The funding problem is where it was and the Iran deal is a rumor I half-doubt. What shifted are the odds with a clear geopolitical catalyst, with rumors, that could tilt the risk in our favor. Enough to swing with a small risk, but clearly not enough to go all-in.
If the environment changes, my book adapts. So it’s adapting. Responsibly.
